

Till: Debit Card for Kids analysis by Appwee
Managing money for a child is less about handing over a card and more about creating a safe space to practise decisions. That is the angle I kept in mind while using Till: Debit Card for Kids, a finance app from Till Financial. It combines a child-focused debit card with an app intended to help kids and teenagers become more thoughtful spenders, so the experience sits somewhere between a pocket-money tool and a supervised introduction to everyday banking.
I like the basic idea because it addresses a real family problem: children need practical experience, but parents usually do not want that experience to involve an unrestricted adult bank account. Till gives families a dedicated environment to discuss spending, monitor activity and build routines. At the same time, it is not a magic solution for teaching financial responsibility. The quality of the experience depends heavily on how parents use the controls and how clearly the family agrees on expectations.
The app is free to install, carries an Everyone age rating and supports Android devices running version 7.0 or later. Optional in-app purchases range from $7.99 to $79.00 per item, so I would check the purchase details carefully before treating the basic download as the complete cost of using the service. The app was released on April 27, 2022, and its current version is 162.41.0.
How Till fits into a family’s money routine
A supervised first step rather than a full banking replacement
My first impression is that Till works best when a parent sees it as a teaching tool with payment functionality, not simply as a replacement for cash. A child can use a debit card in situations where carrying notes and coins is inconvenient, while the parent has a reason to talk through the purchase afterward. That combination makes the app more useful than a basic allowance reminder, because spending becomes something the child can observe and reflect on.
It is also more focused than giving a teenager access to a standard adult account. Traditional banking apps often assume that the account holder already understands balances, recurring payments, card security and the consequences of a declined transaction. A child-oriented product has a different job: it needs to make money visible without making the family’s conversation about money unnecessarily complicated.
In my view, this makes Till particularly suitable for families starting a first structured allowance, preparing a child for independent school trips or helping a teenager practise managing small regular expenses. It is less suitable for someone looking for investment tools, detailed household budgeting or a complete replacement for a conventional current account. The app’s purpose is narrower, and that focus is one of its strengths.
A realistic school-day example
Imagine a teenager receiving money for a school day that includes lunch and an after-school activity. With a normal cash allowance, the parent may only discover a problem when the money is gone. With a card-and-app arrangement, the family can discuss the plan before the day begins: how much is available, which spending is necessary and what should remain afterward.
If the teenager spends more than expected, the useful lesson is not merely that the balance changed. The parent can use the moment to ask whether the purchase was planned, whether it solved an actual need and what choice might have worked better. That conversation is where the educational value lives. The app can make the transaction visible, but it cannot replace the parent’s explanation or the child’s willingness to learn.
I would also use a routine like this before a holiday or a first unsupervised outing. A short discussion about checking the balance, protecting the card and asking for help when something looks wrong is more valuable than simply issuing the card and assuming the child will figure everything out.
What makes the product feel trustworthy
Trust is especially important in a children’s finance app. I would not judge it only by its friendly presentation or by the fact that it has passed a certain popularity threshold. I would want to understand what the parent can see, what the child can do, which actions require adult involvement and how clearly the app presents choices during setup and everyday use.
Till has attracted an average rating of 4.5 from around 2.2 thousand ratings, with more than three hundred written reviews and over 100 thousand installs. Those figures suggest that many families have tried it, but popularity should not be confused with a guarantee that every household will have the same experience. A parent should still read each screen during registration and review the account settings after the family has started using the card.
The developer is Till Financial, which gives the product a clear identity rather than making it feel like an anonymous budgeting utility. Even so, the most meaningful trust signals for me are practical: clear account controls, understandable explanations and visible choices. I prefer an app that lets me pause and consider a decision over one that rushes me through setup with vague wording.
Controls should be part of the teaching plan
The parent-facing side matters as much as the child-facing card. Before introducing Till, I would decide what level of independence the child is ready for. A younger child may need frequent conversations and close review, while an older teenager may benefit from more freedom and less day-to-day intervention. The same account should support a gradual change in responsibility rather than forcing every family into one rigid pattern.
A useful workflow is to begin with a small, clearly defined purpose. For example, the card could initially cover school lunches or a weekly personal allowance. After a few weeks, the parent and child can review what went well and decide whether the child is ready to manage another category of spending. This approach avoids turning the app into a constant surveillance tool and makes each new responsibility feel earned.
I would also encourage parents to check the account together with the child instead of reviewing activity secretly whenever possible. Looking at a transaction side by side teaches the child how to recognise a purchase, question an unfamiliar entry and understand that digital payments leave a record. That is a stronger lesson than simply telling a child that parents can monitor spending.
Where data awareness becomes important
Any finance app deserves a more careful look when personal and payment-related information is involved, and that concern is heightened when a child uses the service. I would read the privacy explanations, permission requests and account notices during setup rather than tapping through them automatically. The important questions are practical: what information is requested, why it is needed, who in the family can view it and which choices can be changed later.
There are several moments when I would slow down. Registration is one, because this is where the family establishes the account and may be asked to provide personal details. Adding or managing a card is another, because payment actions deserve deliberate confirmation. A third is any screen involving optional purchases. Since the app includes in-app purchases, I would make sure the person approving payments understands what is being selected and whether the purchase is necessary for the intended use.
I would not assume that a colourful interface means a child can safely handle every screen alone. Parents should explain why account information must stay private, why a card should not be photographed or shared and what to do if a transaction seems unfamiliar. These habits matter regardless of how trustworthy the app feels, because the weakest part of a financial setup is often an avoidable human mistake.
Visible choices are more valuable than hidden safeguards
One of the strongest ways to evaluate Till is to ask how much control the family can exercise without confusion. Can the parent understand the current setup? Can the child tell what money is available? Are important actions presented in a way that encourages checking before confirming? I would pay attention to these details during real use, because they determine whether the app supports thoughtful decisions or merely speeds up transactions.
For a child, balance awareness is a skill that needs repetition. I would make checking the app part of the allowance routine, perhaps before shopping and again afterward. The goal is not to make the child ask permission for every small purchase forever. The goal is to move from adult guidance toward independent checking, with the app acting as a visible reference point.
For parents, user agency also means knowing when not to intervene. If an older teenager has agreed to manage a defined amount, changing the plan after every purchase can undermine the lesson. I would set clear boundaries in advance: which spending decisions belong to the child, which require discussion and what happens if the money runs out. Till can support that agreement, but the agreement itself must come from the family.
Practical friction parents should expect
The main limitation is that a debit card can make spending easier without automatically making spending wiser. A child may still buy impulsively, misunderstand a balance or focus on the card as a source of money rather than as a tool connected to family rules. Parents who want an entirely hands-off solution may become disappointed, because the educational benefit requires regular involvement.
There is also a potential mismatch between children at different ages. A younger child may need more explanation than the app can provide, while an older teenager may find a heavily supervised setup restrictive. The right balance depends on maturity, family expectations and the kinds of purchases involved. I would not give the same level of freedom to every child simply because the app makes it technically possible.
The optional purchase model is another point to handle carefully. The free price makes trying the app easier, but optional items can complicate a family’s understanding of what is included. I would review the purchase screen with the account owner and avoid assuming that every visible upgrade is essential. A financial education tool should not encourage casual spending while it is teaching children to think carefully about money.
How it compares with cash and ordinary banking apps
Cash is still a strong alternative for younger children because it makes money physically tangible. A child can see the notes disappear and may understand scarcity more quickly than when a card produces a nearly invisible balance change. Cash also avoids app setup and digital account management. Its weakness is that parents have less convenient visibility, and replacing lost money can be frustrating.
A standard bank account may be a better choice for an older teenager who already understands card security and wants broader banking functionality. Conventional banking products can fit more naturally into a young person’s transition toward adult financial life. Their disadvantage is that they may not be designed around parent-child teaching, so the family may need to create its own rules and review process.
Till occupies the middle ground. It is more structured than cash and more child-focused than an ordinary banking app. That makes it appealing when the family wants a dedicated learning stage. I would choose something else if the main goal were detailed personal finance analysis, adult banking services or complete independence. I would also stay with cash if the child is not yet ready to understand digital balances or card responsibility.
Small habits that make the experience better
I found that the most useful approach is to establish a predictable review rhythm rather than checking randomly. A weekly conversation can cover what the child planned to buy, what actually happened and whether the allowance still matches real needs. Keeping the discussion short helps prevent the app from becoming a source of arguments.
Another helpful habit is separating mistakes from emergencies. An unnecessary snack purchase is a teaching moment; a lost card or unfamiliar transaction needs a faster response. I would make sure the child knows the difference and has a simple instruction for contacting the parent. This reduces panic and makes the account’s controls easier to use responsibly.
I would also avoid using the app as a punishment system for unrelated behaviour. Removing access every time a child breaks a household rule may create confusion about whether the card is a financial tool or a reward. Clear, pre-agreed consequences work better. The child should understand which decision caused the consequence and how to regain trust.
Who should choose Till, and who should skip it?
I think Till is a good match for parents who want to introduce a debit card gradually, discuss spending regularly and keep the learning process connected to real purchases. It is especially useful when cash is becoming inconvenient but a full adult banking relationship feels premature. Families that value visible choices and shared account reviews will get more from it than families looking for a completely automatic allowance system.
I would be cautious if the child is too young to understand that a card is linked to limited funds, or if the parent does not have time to explain transactions and review the arrangement. I would also look elsewhere if the household needs sophisticated budgeting, investment features or a broad set of adult banking services. Till’s focused design is not a weakness for its intended audience, but it does make the product a poor fit for needs outside that audience.
My cautious verdict after using it
Till Financial has built an appealing bridge between pocket money and independent spending. The combination of a debit card and a family-oriented app gives children a practical way to practise choices while giving parents a framework for guidance. I appreciate that the product can support gradual responsibility instead of forcing a sudden jump from cash to unrestricted banking.
My recommendation comes with an important condition: treat the app as part of a family process, not as the process itself. Read the setup screens, examine account controls, pay attention to privacy and permission choices, and discuss optional purchases before approving them. Then use real transactions as opportunities to teach planning, security and accountability.
For the right family, Till is a sensible starting point for financial independence. It is free to begin, available for a broad range of Android devices and already used by a substantial community, but those conveniences should not replace careful setup. The best result comes when the card gives a child more responsibility while the parent remains clear, present and deliberate about the boundaries.
Gallery
Till: Debit Card for Kids Pros and Cons
- Parents can monitor spending and manage allowances from one app.
- Kids learn budgeting through real-world spending controls.
- Customizable card settings help limit where and how money is used.
- Allowance transfers can reduce the need for cash or manual payments.
- Useful transaction visibility makes unusual purchases easier to spot.
- Some features may require a paid subscription or additional fees.
- Availability and card terms can vary by country or region.
- Parents must manage funding carefully to avoid declined transactions.
- Younger children may still need guidance to understand spending limits.
- Requires internet access and a compatible device for account management.
Till: Debit Card for Kids Frequently Asked Questions
What is Till: Debit Card for Kids, and how does it work?
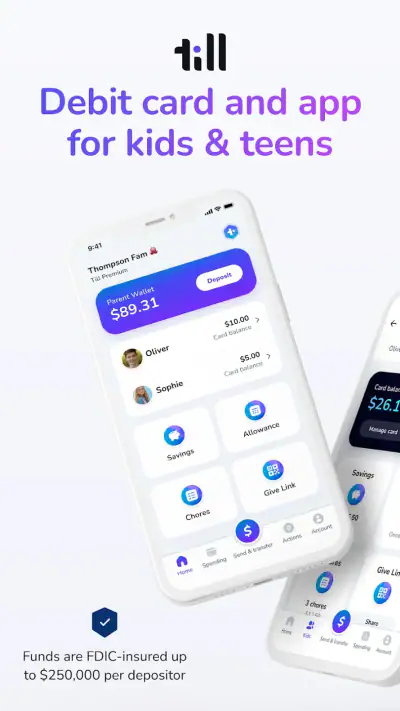
Till is a family-focused money management app designed to help children learn about spending, saving, and earning with guidance from a parent or guardian. After setting up a family account, parents can typically assign allowances or payments, monitor activity, and manage a linked debit card, while children use the app to view their balance and practice everyday money decisions.
Is Till: Debit Card for Kids safe for children to use?
Till is built around parental supervision, which can make it safer than giving a child unrestricted access to a traditional bank account. Parents generally control account settings, review transactions, and receive visibility into spending. However, families should still discuss card security, never share PINs or login details, and check the current privacy policy and security features before signing up.
What age is Till suitable for, and does a parent need to create the account?
Till is intended for children and teenagers who are ready to start learning practical money skills, although the most appropriate age depends on the child’s maturity and the family’s goals. A parent or legal guardian normally needs to open and manage the family account, provide required information, and approve the child’s access. Availability and age requirements may vary by location.
Are there fees for using Till or its debit card?
The total cost can depend on the plan selected, the number of children or cards, and the type of transactions involved. Before downloading or ordering a card, parents should review Till’s current pricing carefully, including subscription charges, replacement-card fees, ATM costs, transfer limits, and any optional features. Terms may change, so the official app listing and website are the best sources.
Can parents control where their child spends money with Till?
Till is designed to give parents oversight of a child’s spending, but the exact controls depend on the current version of the service and the card’s rules. Parents may be able to review transactions, manage allowances, and receive notifications, while certain merchant categories or payment options could have restrictions. Families should check the available controls before relying on Till for unsupervised spending.














